Debt Consolidation With Home Equity: Costs, Risks, and Refinancing Options
Delving into Debt Consolidation With Home Equity: Costs, Risks, and Refinancing Options, this introduction immerses readers in a unique and compelling narrative, with a casual formal language style that is both engaging and thought-provoking from the very first sentence.
Exploring the concept of using home equity for debt consolidation, this topic sheds light on the costs, risks, and refinancing options associated with this financial strategy.
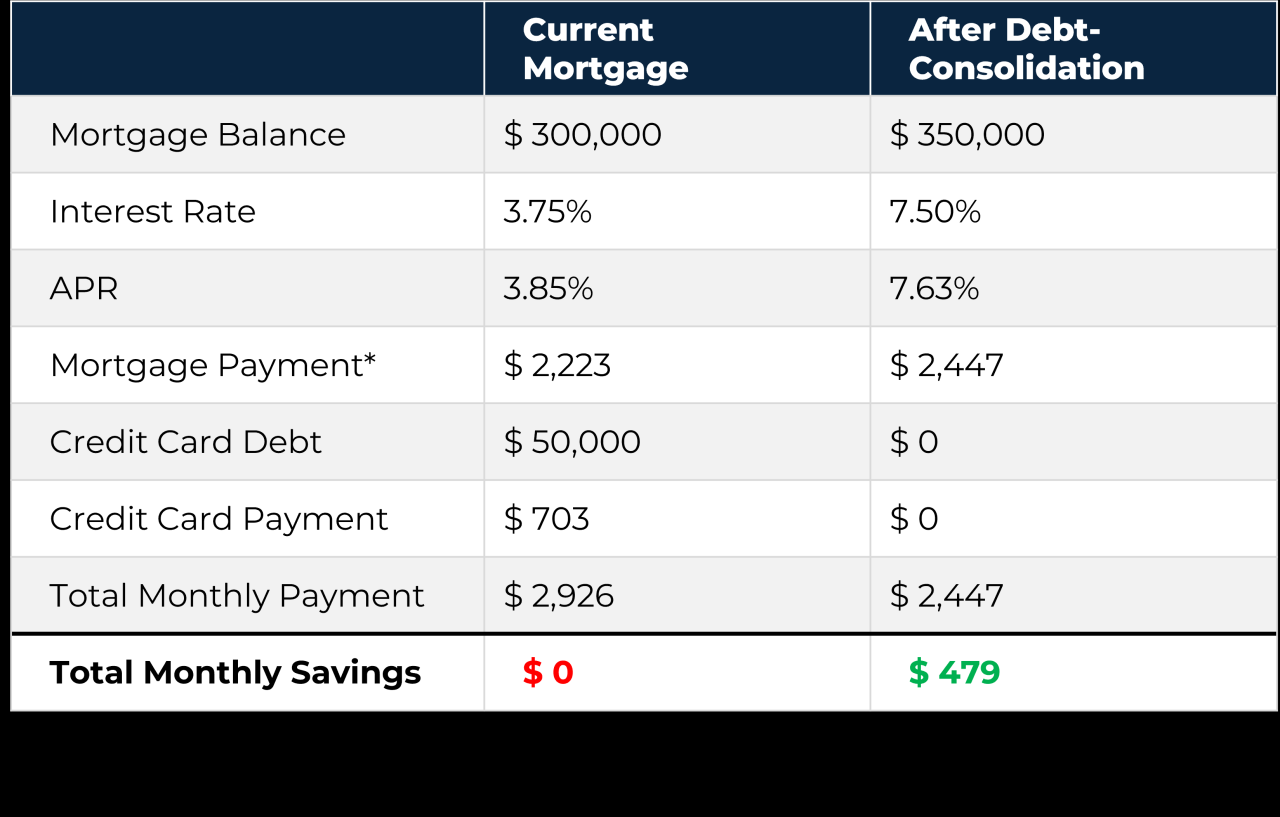
Debt consolidation with home equity is a financial strategy that involves using the equity in your home to pay off high-interest debts such as credit card balances, personal loans, or medical bills. By leveraging the value of your home, you can potentially save money on interest payments and simplify your debt repayment process.
When considering debt consolidation with home equity, it is crucial to understand the various costs involved in this financial strategy. By leveraging the equity in your home to pay off high-interest debts, you can potentially save money in the long run.
However, it is essential to weigh the costs against the benefits to determine if this option is right for you.
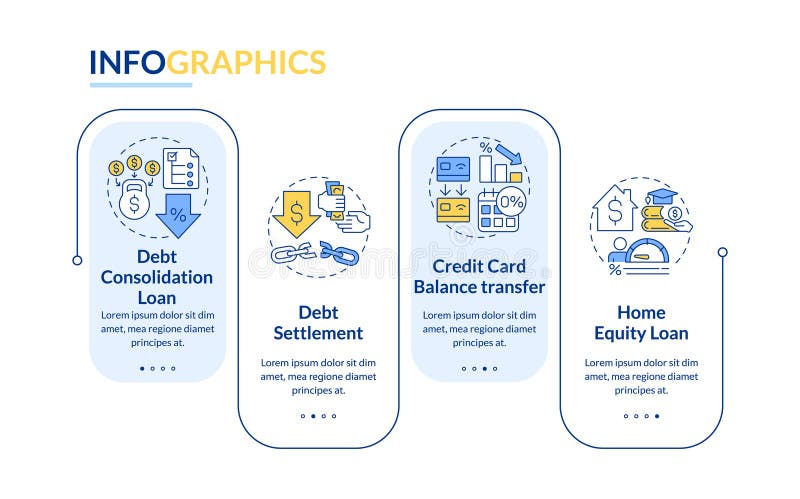
When considering debt consolidation using home equity, it is crucial to be aware of the potential risks involved. While it can provide a solution for managing multiple debts, there are several factors to consider before leveraging your home’s equity.
When it comes to refinancing options for debt consolidation with home equity, homeowners have a few choices to consider. Two common options include refinancing through a home equity loan or a home equity line of credit. Each option has its pros and cons, so it’s important to weigh them carefully before making a decision.
What is the difference between a home equity loan and a home equity line of credit (HELOC)?
A home equity loan provides a lump sum of money with a fixed interest rate, while a HELOC allows you to borrow money as needed up to a certain limit with a variable interest rate.
Can I lose my home if I default on a home equity loan used for debt consolidation?
Yes, defaulting on a home equity loan can lead to foreclosure, putting your home at risk. It’s crucial to make timely payments to avoid such consequences.
How do I determine if using home equity for debt consolidation is the right choice for me?
Consider factors like interest rates, total costs, and your ability to repay the loan. Consulting with a financial advisor can help you make an informed decision.