Building Insurance vs Homeowners Insurance: Coverage, Costs, and Key Differences
Exploring the realm of Building Insurance vs Homeowners Insurance: Coverage, Costs, and Key Differences, this piece invites readers into a world of insurance nuances and distinctions. Brace yourself for an enlightening journey through the intricacies of these two essential forms of protection.
The following paragraphs will shed light on the fundamental aspects of building insurance and homeowners insurance, offering insights into their coverage, costs, and key disparities.
Building Insurance is a type of property insurance that provides coverage for the structure of a building, including walls, roof, floors, and foundations. It typically covers damages caused by events such as fire, lightning, explosions, and vandalism.Homeowners Insurance, on the other hand, is a comprehensive policy that includes coverage for the structure of the home as well as personal belongings, liability protection, and additional living expenses in case the home becomes uninhabitable.
It provides a wider range of coverage compared to Building Insurance.
Building insurance and homeowners insurance both offer protection against various risks, but they differ in the specific perils they cover. Let’s take a closer look at the coverage provided by each type of insurance.
Building insurance typically covers the structure of the home, including the walls, roof, floors, and foundation. It protects against perils such as fire, lightning, windstorm, hail, explosion, and vandalism. In case of damage or destruction to the building due to these covered perils, building insurance will help cover the repair or rebuilding costs.
Homeowners insurance not only covers the structure of the home like building insurance but also includes coverage for personal belongings, liability protection, and additional living expenses. The specific perils covered by homeowners insurance are similar to building insurance, such as fire, theft, vandalism, and certain natural disasters like earthquakes and floods.
While building insurance and homeowners insurance have specific differences in coverage, there are some common areas where they overlap. Both types of insurance typically cover damage caused by fire, lightning, windstorm, and vandalism. Additionally, they may provide coverage for personal property inside the home, albeit to different extents depending on the policy.
Building insurance and homeowners insurance costs are influenced by various factors. Let’s explore the key elements that determine the cost of each type of insurance.
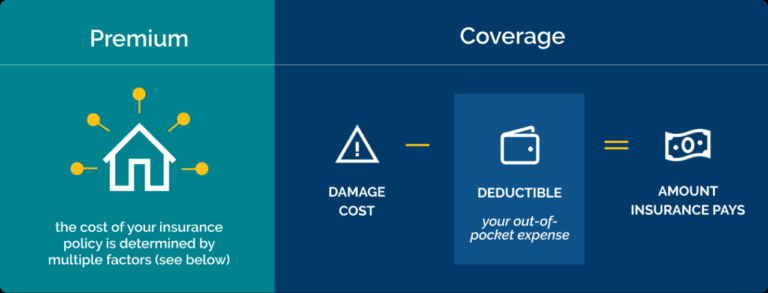
Building insurance premiums are determined by factors such as the location of the property, the age and condition of the building, the reconstruction cost, the materials used, and the level of coverage selected. Additionally, the proximity to natural disaster-prone areas can impact the cost of building insurance.
Homeowners insurance premiums are influenced by factors such as the location of the property, the type of coverage selected, the value of personal belongings, the age of the policyholder, and the deductible amount chosen. Additionally, factors like the presence of safety features in the home can impact the cost of homeowners insurance.
The typical cost range for building insurance can vary widely depending on the factors mentioned above. On average, building insurance premiums can range from $500 to $2,000 per year.Similarly, the cost of homeowners insurance also varies based on the factors influencing the premium.
On average, homeowners insurance premiums can range from $800 to $3,000 per year.
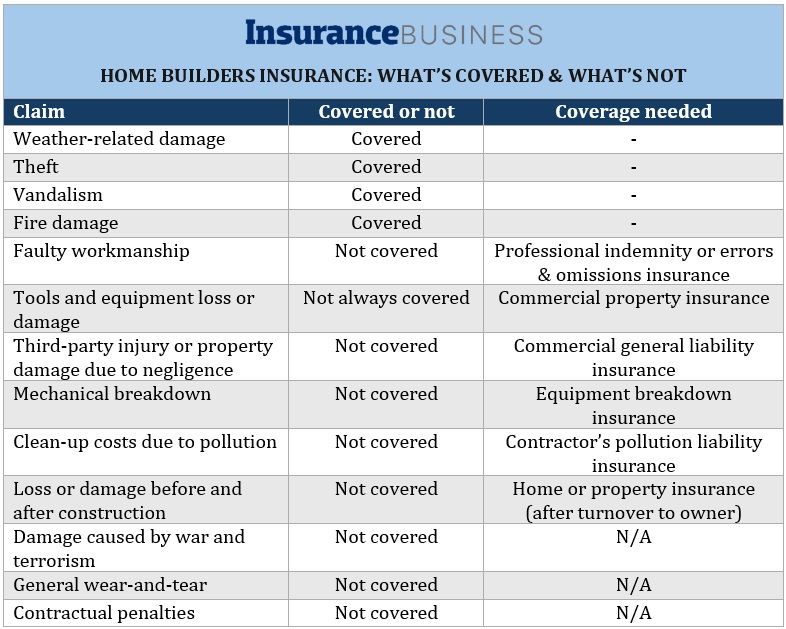
Building Insurance and Homeowners Insurance have key differences in coverage, unique features, and suitability for various scenarios.
What perils are covered by Building Insurance and Homeowners Insurance?
Building Insurance typically covers structural damage from events like fire or vandalism, while Homeowners Insurance extends coverage to personal property and liability.
What factors influence the cost of Building Insurance and Homeowners Insurance?
The age of the building, construction materials used, and location can impact Building Insurance costs, whereas Homeowners Insurance costs are influenced by the value of personal belongings, liability coverage limits, and the home’s location.
Can you explain common areas of coverage between Building Insurance and Homeowners Insurance?
Both types of insurance may provide coverage for damages caused by certain natural disasters, like storms or lightning strikes, depending on the policy.